

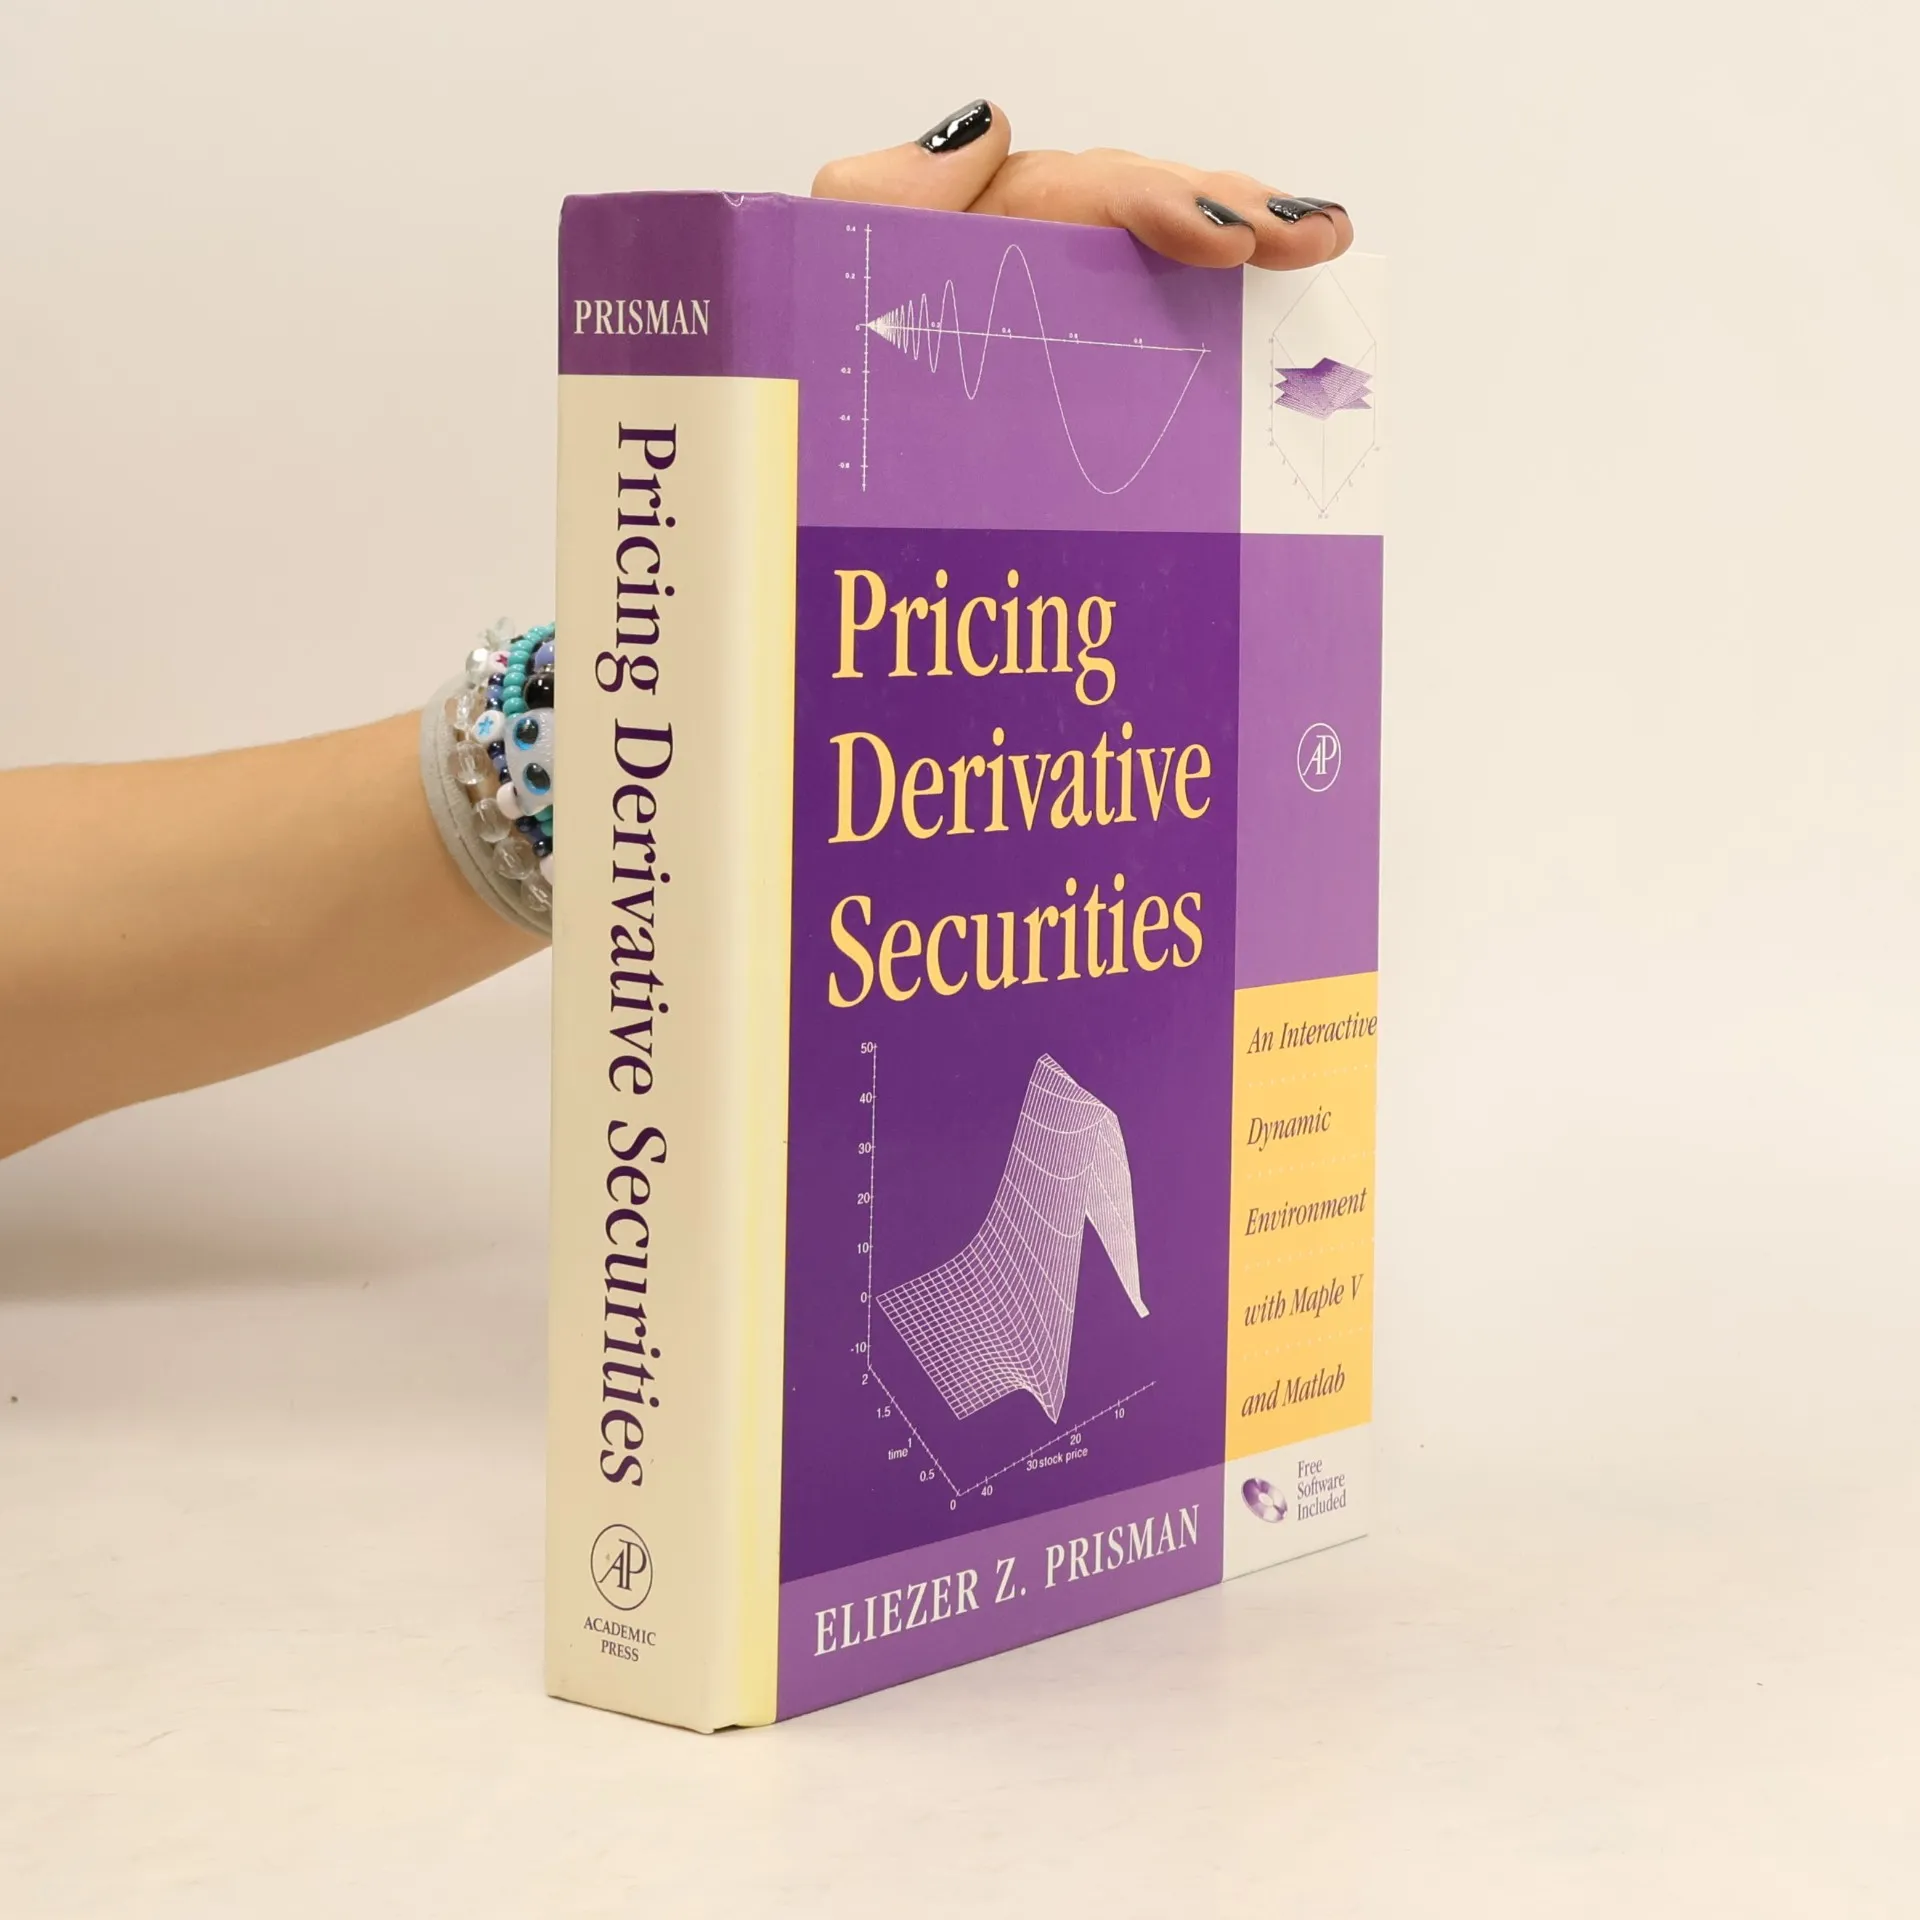


Pricing Derivative Securities
An Interactive, Dynamic Environment with Maple V and Matlab - Free Software Included
Auteurs
Parameters
- 756bladzijden
- 27 uur lezen
Meer over het boek
Pricing derivatives theory is brought to life in this interactive financial pricing experience. The book is driven by a no-arbitrage perspective within a one-period state-preference model, utilizing Maple® and Matlab® programs to help readers visualize payoffs and navigate various constraints. With clear explanations and rich illustrations, this resource teaches core theoretical concepts often obscured by complex terminology and institutional details. Readers can engage with the electronic packages indefinitely, using the book and its solutions manual as a tutorial to tackle increasingly complex problems. Key features include an enclosed CD-ROM with the student version of Maple V, offering a dynamic learning environment that encourages hands-on experience. Students can enhance their learning by modifying commands in online files, allowing for experimentation with applications and reader-generated examples alongside those provided. The book equips readers with the framework and tools based on the no free lunch concept to analyze various scenarios related to derivative securities, including those not explicitly covered. Basic concepts of stochastic calculus are illustrated through animations, simulations, and three-dimensional graphs, simplifying mathematical complexities. Additionally, the MATLAB® Graphic User Interface brings theoretical material to life, enhancing the learning experience.
Een boek kopen
Pricing Derivative Securities, Eliezer Z. Prisman
- Taal

- Jaar van publicatie
- 2000
- Bindwijze
- (Hardcover),
- Staat van het boek
- Beschadigd
- Prijs
- € 4,21
Betaalmethoden
Nog niemand heeft beoordeeld.
- Titel
- Pricing Derivative Securities
- Ondertitel
- An Interactive, Dynamic Environment with Maple V and Matlab - Free Software Included
- Taal
- Engels
- Auteurs
- Eliezer Z. Prisman
- Uitgever
- Academic press
- Jaar van publicatie
- 2000
- Formaat
- Hardcover
- Aantal pagina's
- 756
- ISBN10
- 0125649150
- ISBN13
- 9780125649155
- Reeks
- Categorieën
- Aantekening
- Pricing derivatives theory is brought to life in this interactive financial pricing experience. The book is driven by a no-arbitrage perspective within a one-period state-preference model, utilizing Maple® and Matlab® programs to help readers visualize payoffs and navigate various constraints. With clear explanations and rich illustrations, this resource teaches core theoretical concepts often obscured by complex terminology and institutional details. Readers can engage with the electronic packages indefinitely, using the book and its solutions manual as a tutorial to tackle increasingly complex problems. Key features include an enclosed CD-ROM with the student version of Maple V, offering a dynamic learning environment that encourages hands-on experience. Students can enhance their learning by modifying commands in online files, allowing for experimentation with applications and reader-generated examples alongside those provided. The book equips readers with the framework and tools based on the no free lunch concept to analyze various scenarios related to derivative securities, including those not explicitly covered. Basic concepts of stochastic calculus are illustrated through animations, simulations, and three-dimensional graphs, simplifying mathematical complexities. Additionally, the MATLAB® Graphic User Interface brings theoretical material to life, enhancing the learning experience.